An insurance roof inspection is a documented look at your roof’s condition, done either for an insurer deciding whether to write or renew your policy, or for you after a storm to show what damage exists. Insurers typically ask for one when a roof reaches a certain age, when you transfer a policy, or after a claim. A professional inspection gives you a dated report with photos and measurements that you can hand to your carrier. Below is how each case works, what the report should contain, how to prepare, and what you may pay.
TL;DR
- Insurers commonly trigger roof inspections at age thresholds of 15, 20 or 25 years, after a claim, at a policy transfer or at renewal review.
- A good report documents wind creasing, hail dents, granule loss and attic water intrusion, with photos and measurements.
- Photograph damage before cleanup, keep every message with your insurer, and hold off on permanent repairs until the insurer has inspected.
- A standalone four-point inspection typically runs $100 to $300, depending on market and home size. Our roof inspections and estimates are free.
- Inspect yearly, and again after any hail or high-wind event.
Table of Contents
- What an insurance roof inspection is
- When insurers ask for a roof inspection
- What the inspector checks
- What a useful inspection report contains
- How to prepare before the inspection
- What a roof inspection costs
- How often to have your roof inspected
- Why this matters financially
- Perspective
- Get your roof inspected
- FAQ
- Sources
What an insurance roof inspection is
The phrase covers two different jobs, and mixing them up causes most of the confusion.
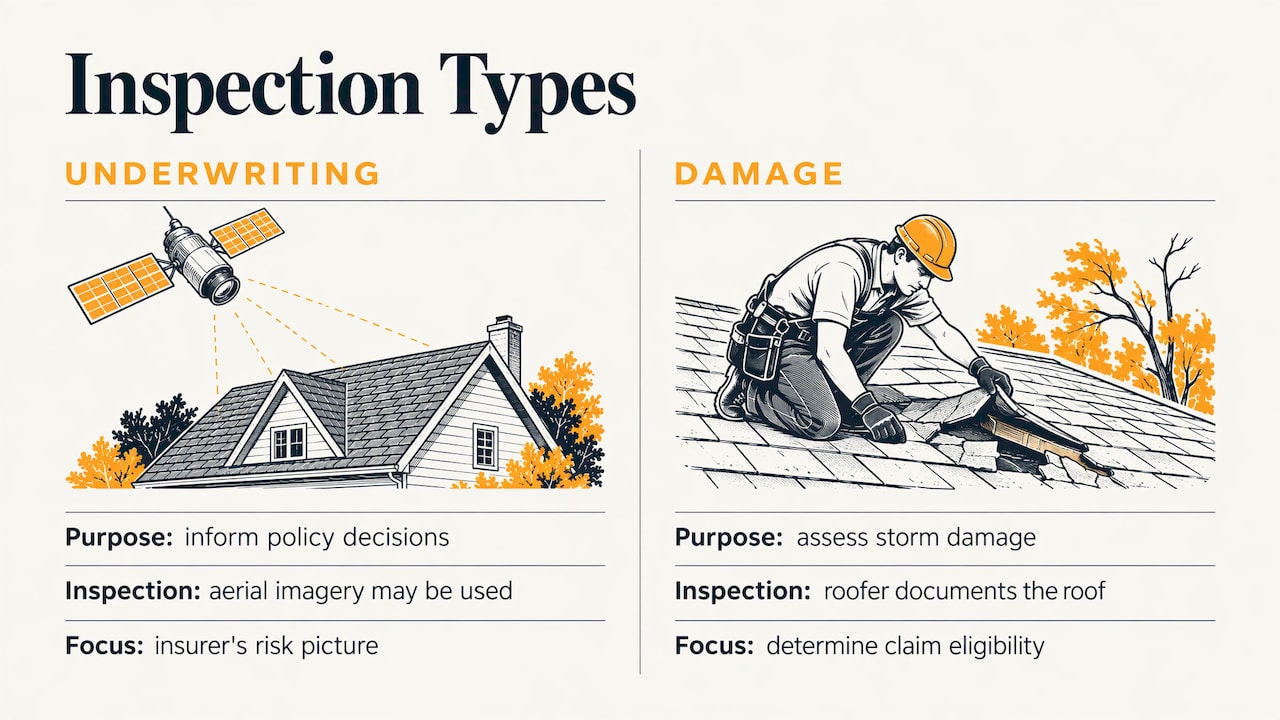
Underwriting inspection. Your insurer wants to know what it is insuring. It gathers information about the roof’s condition to decide whether to write, renew or reprice the policy. Many carriers now do part of this without visiting. Insurers use aerial imagery from drones and satellites to photograph properties, and that data can inform underwriting decisions.
Damage inspection. You think a storm hurt your roof. A roofing professional climbs up, documents what is there, and tells you whether the damage looks serious enough to justify a claim. Industry sources describe a roof inspection report as evidence of structural and cosmetic issues that helps determine whether damage qualifies for a claim.
The first protects the insurer’s risk picture. The second protects your wallet. In North Texas, with hail and straight-line wind a regular part of spring, the second one is the inspection most homeowners need.
When insurers ask for a roof inspection
There is no single national rule. Carriers set their own triggers, and the common ones are:
- Roof age. Thresholds of 15, 20 or 25 years are common. The Insurance Information Institute notes that if your roof is over 20 years old when you apply for home or business insurance, most insurers will require it to pass an inspection.
- A recent claim. The carrier may want to see the roof’s current state before renewing.
- A policy transfer or purchase. New owners and new carriers both look at the roof.
- Renewal review. Some insurers periodically reassess older roofs.
State-specific versions exist too. In Florida, for example, a four-point inspection is commonly required when a policy is issued or renewed. It evaluates roofing, electrical, plumbing and HVAC systems to judge insurability. That is a Florida practice. Texas homeowners should ask their own agent which inspection their carrier wants.
What happens after an underwriting inspection
If the roof falls short, insurers may require repairs within 30 to 90 days, change policy terms such as raising deductibles, or decline to renew. That is why a report from a qualified roofer, with specific findings and a repair plan, is worth having before the insurer’s deadline starts.
The Insurance Information Institute also notes that some insurers may ask for proof of a routine inspection and professional maintenance. Keeping dated reports in a folder makes that conversation easy.
What the inspector checks
A thorough inspection covers the exterior, the roof surface, the penetrations and the attic. After a storm, a damage assessment typically documents:
- Wind damage: creased shingles, lifted edges, missing tabs.
- Hail damage: dents in metal components, bruising and granule loss on shingles.
- Water intrusion: stains, damp insulation or daylight in the attic.
- Structural impacts: sagging decking or compromised framing.
The NRCIA’s guide to storm damage assessment reports describes these findings as supported by photographs and measurements. That support matters because an adjuster reviews evidence, not impressions.
Beyond the surface, a good inspector also looks at flashing around chimneys and vents, valleys, gutters and drip edges, and the condition of sealants. These are the places leaks start long before shingles fail. If you want to walk your own roof line from the ground first, our DFW roof inspection checklist lists what to look for, and our guide to assessing roof damage severity helps you sort cosmetic wear from real problems.
What a useful inspection report contains
When you hand a report to an insurer, it needs to stand on its own. Look for these elements:
- Date, address and inspector details. A report without a date cannot show when damage occurred relative to a storm.
- Roof description. Material, approximate age, pitch and layers.
- Photos tied to locations. Each photo labeled by slope or component, not a loose pile of images.
- Measurements. Size of damaged areas, number of impacts in a test square, length of lifted or creased runs.
- Cause where identifiable. Wind, hail, water, age-related wear, or installation issues. Separating storm damage from wear is what adjusters focus on.
- Recommendation. Repair, partial replacement or full replacement, and what is needed to restore or preserve the roof.
If your inspection report needs to support a claim, ask the inspector to separate documented storm damage from general aging. Clear categories make a review faster for everyone.
How to prepare before the inspection
Preparation is mostly about protecting evidence and your policy rights. The National Association of Insurance Commissioners (NAIC) gives consistent consumer guidance on this.
Document before you clean up
Take photographs or video before cleanup or repairs, keep a record of communications with your insurer, and save receipts. Before removing debris or belongings, document losses and make a list of damaged items.
Stop further damage, but hold permanent repairs
Make the repairs needed to prevent additional damage, such as a tarp over an opening. The NAIC guidance is not to make permanent repairs before the insurer has inspected and approved them. If water is coming in, our guides to patching a roof hole from the inside and small leaks cover temporary measures. For active leaks, our emergency roofing service exists for that situation.
Read your policy before storm season
Wind and hail deductibles can be higher than your primary deductible, according to a state insurance regulator’s guidance. Know your number before the storm, and call your agent or carrier with questions.
Watch what you sign
Be careful about who offers to inspect your roof and what they ask you to sign. In Florida, state law bars a contractor from offering a homeowner a rebate, gift or deductible waiver in exchange for permission to inspect the roof. That is a Florida rule, but the habit it points to is sound anywhere: a straightforward inspection should not require you to give anything up. Our guide to hiring a qualified roof inspector covers credentials and questions to ask.
What a roof inspection costs
Prices depend on who inspects, your market, and the size and complexity of the roof. The one figure we can anchor to an official source is for a standalone four-point inspection, which typically costs $100 to $300. The same source notes that the price varies with the inspector, local market, region and home size, and that it may be folded into a package price when done with other services.
A few things push the price up or down in practice:
| Factor | Effect on price |
|---|---|
| Roof size and pitch | Larger, steeper roofs take longer and need more safety setup |
| Roof material | Tile, metal and low-slope commercial systems need different methods |
| Report depth | A photo-rich written report takes more time than a verbal summary |
| Add-ons | Attic review, drone imagery or moisture checks can add cost |
| Bundled services | An inspection tied to repair work is sometimes priced into the job |
At James Kate Roofing & solar, roof inspections and estimates are free. We do not publish a price for repair or replacement work, because it depends on the roof in front of us.
How often to have your roof inspected
The Insurance Information Institute advises having your roof inspected yearly, especially if it is 15 or more years old. It also advises checking for missing or damaged shingles after a storm and scheduling inspections when you notice leaks, missing shingles or sagging areas.
A practical maintenance schedule for North Texas looks like this:
- Every spring, after the worst of the hail season, a professional or ground-level check.
- Every fall, before winter, to catch loose flashing and clogged gutters.
- After any hail or high-wind event, even if nothing looks wrong from the yard. Damage is often invisible from the ground.
- Before a policy renewal or home sale, especially on a roof past 15 years.
If you already see signs of trouble, our roof damage assessment guide shows how to check, document and decide what to do next. Homeowners around Granbury can use our post-storm inspection guide.
Why this matters financially
Roofs are where storm losses concentrate. Triple-I reports that roof-related damage accounts for roughly 70 to 90 percent of insured residential catastrophic losses. That is why insurers scrutinize roofs closely and why a documented, current condition record is useful at both renewal and claim time.
It also explains a common surprise: an insurer can respond to an old or worn roof by changing your terms or declining to renew, not only by denying a claim. A repair plan done early is cheaper than a forced replacement on the insurer’s schedule. If your shingles are marketed with a long warranty, read our 25-year shingle lifespan versus warranty explainer, since the warranty number and the real service life are different things.
Perspective
Most homeowners call a roofer after the insurer has already raised a concern, or after a storm when everyone on the street is calling at once. We think the better order is the reverse. Know your roof’s condition first, with a dated record, and every later conversation with your carrier gets easier.
That is the idea behind how we work. We are a GAF Master Elite® contractor, and we hold the GAF President’s Club Award and IKO Craftsman Premier Contractor status. We use that training to inspect methodically and explain findings in plain terms, so you understand your roof whether the answer is a minor repair or a replacement.
Our instant roofing quote tool looks at historical weather data to help you see whether severe storms may have affected your roof. It is a starting point, and a walk-through on the roof is what confirms it. We offer free inspections and estimates because you should understand your roof before you decide anything. For residential replacements, we back our work with a transferable 15-year workmanship warranty, which matters when you sell the house or when an insurer wants to see a roof in good standing.
>
Dustin Eatman
Get your roof inspected
If your insurer has asked for an inspection, a storm has just come through, or your roof is past the 15-year mark, we can inspect it and give you a clear, photo-supported picture of its condition. Our roof inspection service is free and covers homes across Dallas, Tarrant, Denton, Collin and the other North Texas counties we serve. Commercial owners and property managers can request a commercial roof inspection and estimate.
Local pages are available for Denton, Frisco and Grand Prairie.
FAQ
Do I need a roof inspection to file an insurance claim?
Not every claim requires one, but a professional inspection gives you documented damage, measurements and photos to work from. Your insurer will send its own adjuster as well. Check your policy or call your agent about your carrier’s process, and photograph the damage before any cleanup.
How much does a roof inspection for insurance cost?
A standalone four-point inspection typically costs between $100 and $300, according to Florida’s insurance consumer advocate, and the price shifts with local market and home size. Prices for other inspection types vary by roof and report depth. Our roof inspections and estimates are free.
Can an insurer cancel or refuse to renew because of my roof?
Yes, it can. After an inspection, insurers may require repairs within a set window, change terms such as deductibles, or decline to renew if the roof’s condition is unacceptable. Getting repairs scoped early, with a written report, gives you time to respond.
Should I repair storm damage before the adjuster comes?
Only what is needed to prevent more damage, such as a temporary tarp. Photograph everything first, save receipts, and wait for the insurer’s inspection and approval before permanent repairs, as consumer guidance from the NAIC advises.
How often should a roof be inspected?
At least once a year, and more attentively once the roof is 15 years old or older. Add an inspection after any hail or high-wind storm, and when you see leaks, missing shingles or sagging.
Sources
- Insurance Roof Inspections: What to Expect
- How Your Roof Influences Your Home and Business Insurance
- Triple-I Roof Toolkit 2024
- Four Point Inspection Guide, Florida CFO
- How to read a storm damage roof assessment report, NRCIA
- After a storm, read the fine print, NAIC
- Wind and hail deductible tip, New Mexico Office of Superintendent of Insurance
- Contractor-Residential Property FAQs, Florida CFO
- Storm-Resistant Roof Efforts Gain Ground, Triple-I
Recommended
- Your Guide to Hiring a Qualified Roof Inspector
- Roof Damage Assessment: How to Check, Document and Decide
- The DFW Roof Inspection Checklist for Savvy Homeowners
- Choosing the Best Professional Roofing Company: A Comprehensive Look
Dustin Eatman is a seasoned roofing professional with deep, hands-on expertise that spans residential and commercial roofing, insurance solar, and long-term roof asset management. As the owner of James Kate Roofing & solar in the Dallas–Fort Worth metroplex, he’s built a reputation for diagnosing roof systems accurately, communicating clearly, and executing projects with a high standard of workmanship and documentation. Dustin understands the technical details that make roofs perform—proper underlayment selection, slope and drainage considerations, ventilation strategy, flashing and penetration detailing, and manufacturer-specific installation requirements—because he’s worked through the real-world challenges that cause leaks, premature wear, and warranty issues. He’s equally fluent in the operational side of roofing: jobsite planning, quality control, safety, material ordering, crew coordination, and customer experience from inspection to closeout. In insurance-related projects, Dustin brings practical knowledge of claim workflows, adjuster meetings, scope alignment, supplements, and the importance of photo evidence and thorough records, helping property owners navigate stressful situations with confidence. For commercial clients—especially property and facility managers—he emphasizes proactive maintenance and targeted repairs that reduce disruption, extend roof life, and prevent expensive interior damage. Dustin also stays focused on doing things the right way: educating customers on realistic options, setting expectations, and prioritizing solutions that hold up over time rather than quick fixes. That blend of technical skill, field experience, process discipline, and owner-level accountability is what makes Dustin Eatman a trusted expert in the roofing industry.